Get our plumbing guides firstAdd U.T. Trenchless as a preferred source and see our posts more often in Google Top Stories.
Add as a preferred source on GoogleIs pipe relining covered by insurance? Usually not under a standard Texas homeowners policy. Most policies exclude wear and tear, which is why pipes typically need relining in the first place. Coverage for pipe relining in Texas more often comes from an optional service line endorsement or a separate warranty plan. A sewer backup endorsement may help with damage inside the home, but that is a different thing.
This is one of the first questions homeowners ask after a camera report shows a cracked or root filled sewer line. The honest answer depends on your policy, your endorsements and what caused the damage.
This guide explains how Texas homeowners policies generally treat sewer lines, the three kinds of coverage that can come into play, and how to approach a claim. We are plumbers, not insurance agents or lawyers, so treat this as a starting point for a conversation with your agent, not a coverage opinion.
Not legal or insurance advice
Only your policy language and your insurance company can decide coverage. Read your declarations page and endorsements, and ask your agent in writing if anything is unclear.
What’s in this guide
- The short answer: the cause decides the coverage
- Three kinds of coverage that can apply
- Who owns the line in El Paso
- Is pipe relining covered by insurance in Texas if you have the right endorsement?
- How to approach a sewer line claim
- What to do next
- Questions Texas homeowners ask about insurance and pipe relining
- Keep reading
The short answer: the cause decides the coverage
Insurance is built around sudden, accidental events. Most sewer laterals that need relining did not fail suddenly. They cracked over decades, let roots in at the joints or corroded from the inside. Insurers generally treat that as deterioration, not an accident.
The Texas Department of Insurance home insurance guide lists “wear and tear” and “a continuous water leak” among the things most policies do not cover. It also notes that most policies do cover the “sudden and accidental release of water.” That gap explains most denied pipe claims.
So when people ask whether pipe relining is covered by insurance in Texas, the real question is which coverage you have. The base policy rarely pays to renew an old line.
Three kinds of coverage that can apply
Homeowners often lump everything together as “my insurance.” In practice, three different products can touch a sewer problem, each aimed at a different part of the loss.
| Coverage type | What it is generally aimed at | Common limits on the pipe itself |
|---|---|---|
| Standard homeowners policy | Sudden and accidental damage to the home | Wear and tear and continuous leaks are typically excluded |
| Backup of sewers or drains endorsement | Damage inside the home when a sewer or drain backs up | Focused on the resulting damage; check whether it pays for the line |
| Service line coverage endorsement | Repairing or replacing underground utility lines, including sewer pipes | Often a set limit such as $10,000 or $25,000; excludes pipes under the home |
| Utility warranty plan | Repair of exterior water and sewer lines under a service contract | A contract, not insurance; terms set by the provider |
Backup of sewers or drains
TDI lists “backup of sewers or drains” as one of the common endorsements Texas insurers offer. A Verisk announcement from when Texas approved the ISO homeowners program described the backup endorsement as covering “water damage from constant or repeated seepage or leakage of water from a household appliance or from a sewer or drain backup.” In other words, it is mainly about cleanup and repair inside the house, not about renewing the pipe.
Service line coverage
This is the endorsement most likely to help with the pipe itself. The Texas Office of Public Insurance Counsel explains that service line coverage “covers the cost of repairing or replacing utility lines, excavation, and landscape restoration in the event of a loss.” OPIC says covered causes typically include wear and tear, rust, corrosion, decay, deterioration, tree root damage and collapse.
There are two catches. OPIC notes the coverage usually has a limited amount with a special deductible, giving the example of “$10,000 or $25,000 of coverage, with a $500 deductible.” It also says the coverage generally does not apply to “wires or pipes that run through or under your home,” so a drain line under your slab may fall outside it.
Pipe Relining in El Paso
Want a straight answer about your pipes?
Every U.T. Trenchless job starts with a camera inspection and a photo report, so you see the problem before you decide on a fix. Licensed Master Plumber Ubaldo Torres leads the work.
Who owns the line in El Paso
Coverage only matters for pipe you are responsible for. El Paso Water’s customer responsibilities say the customer is responsible for “the sewer service line from the tap at the main into the property.” That is often most of the lateral.
El Paso Water also promotes a service line warranty program through Service Line Warranties of America, noting that “it is your responsibility as a homeowner to pay for any line repairs on your property.” A warranty plan is a service contract, not insurance, so read what methods and limits it allows. Our guide on who is responsible for the sewer line in El Paso covers ownership in more detail.
Is pipe relining covered by insurance in Texas if you have the right endorsement?
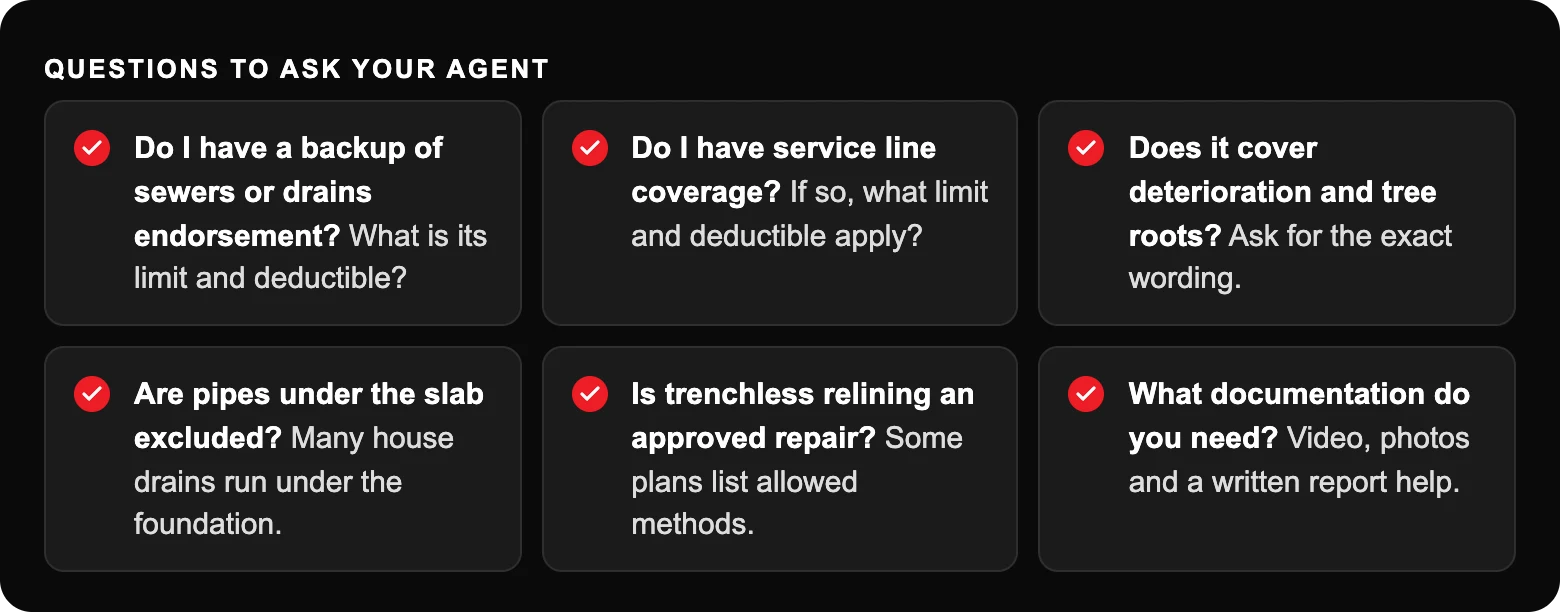
Sometimes. Even when a service line endorsement or warranty applies, the plan may set limits on method, cost or who does the work. Ask whether trenchless relining is an approved repair, whether the limit covers the full length of your line and whether access work, cleanouts or restoration count against the same limit.
Trenchless relining can help here: with no trench through the yard or driveway, there is less restoration cost against the limit. Our pipe relining service renews the line from the inside through existing access points where the pipe allows it.
How to approach a sewer line claim
If a backup has already happened, a few steps protect your home and your claim. TDI advises homeowners to “make only temporary repairs to protect your house and belongings” and warns: “Don’t make permanent repairs.” An insurer may deny a claim if permanent work is done before it can inspect.

Documentation is where a plumber can genuinely help. Every job we do starts with a high resolution video camera inspection, and findings are recorded in a photo report before we recommend any repair. We cannot tell you what your policy covers, but we can show clearly what failed and why. For what to do in the first hour of a backup, see what counts as a plumbing emergency.
If you disagree with a decision
TDI runs a consumer help line at 800.252.3439. Texas OPIC also publishes plain language guides on claims and policyholder rights.
What to do next
- Pull your policy and look for backup of sewers or drains and service line coverage endorsements.
- Have the line inspected on camera so the cause and location of damage are documented.
- Ask your agent the questions above, in writing.
- Make only temporary repairs until the insurer has had a chance to inspect.
- If you are buying a home, consider a sewer scope first; see whether a sewer camera inspection is worth it before buying.
- Call 915.858.0166 or use our contact page to Request Service.
Questions Texas homeowners ask about insurance and pipe relining
Does homeowners insurance cover tree roots in a sewer line?
Under a standard policy, root damage is usually treated as gradual deterioration and excluded. Texas OPIC says optional service line coverage typically does include tree root damage, subject to its limit and deductible, so check whether you have that endorsement.
Does insurance cover a collapsed sewer pipe?
It depends on the cause and your coverage. A standard policy often excludes collapse from age or deterioration. OPIC lists collapse among the causes service line coverage typically includes. Ask your agent how your specific policy treats it.
Is sewer backup coverage the same as sewer line coverage?
No. A backup of sewers or drains endorsement is aimed at damage inside your home when wastewater backs up. Service line coverage is aimed at repairing or replacing the underground pipe. Many homeowners have neither unless they added it.
Will insurance pay for the camera inspection?
That varies by policy and by whether the loss is covered. Keep the invoice and report either way, since the adjuster will likely want to see what caused the damage.
Can I add sewer line coverage after I find a problem?
Coverage generally applies to losses that happen after it takes effect, and insurers may exclude known existing damage. If your line is still working, ask your agent now rather than after a failure.
Serving El Paso, Horizon City, Socorro and Las Cruces
Talk to a family owned trenchless team with 40+ years in the trade
Tell us what is going on and we will tell you what the camera shows, what your options are, and what we would do if it were our own property. Learn more about our pipe relining service.
Keep reading
Sources
- Home insurance guide, Texas Department of Insurance.
- Service Line Coverage, Texas Office of Public Insurance Counsel.
- Customer Rights and Responsibilities, El Paso Water.
- Service Line Warranty Program, El Paso Water.
- Texas Approves ISO Homeowners 2000 Program, Verisk.